Three kinds of involvement, one clean separation
Volunteering, coaching and employment follow different rules. MetronHR records working time where it is mandatory and keeps contracts, times and assignments in one place.
No credit card required · Cancel monthly
- Employees and mini-jobbers each with their own contract
- Hours per person for payroll instead of slips with the treasurer
- Recording duty met where it applies
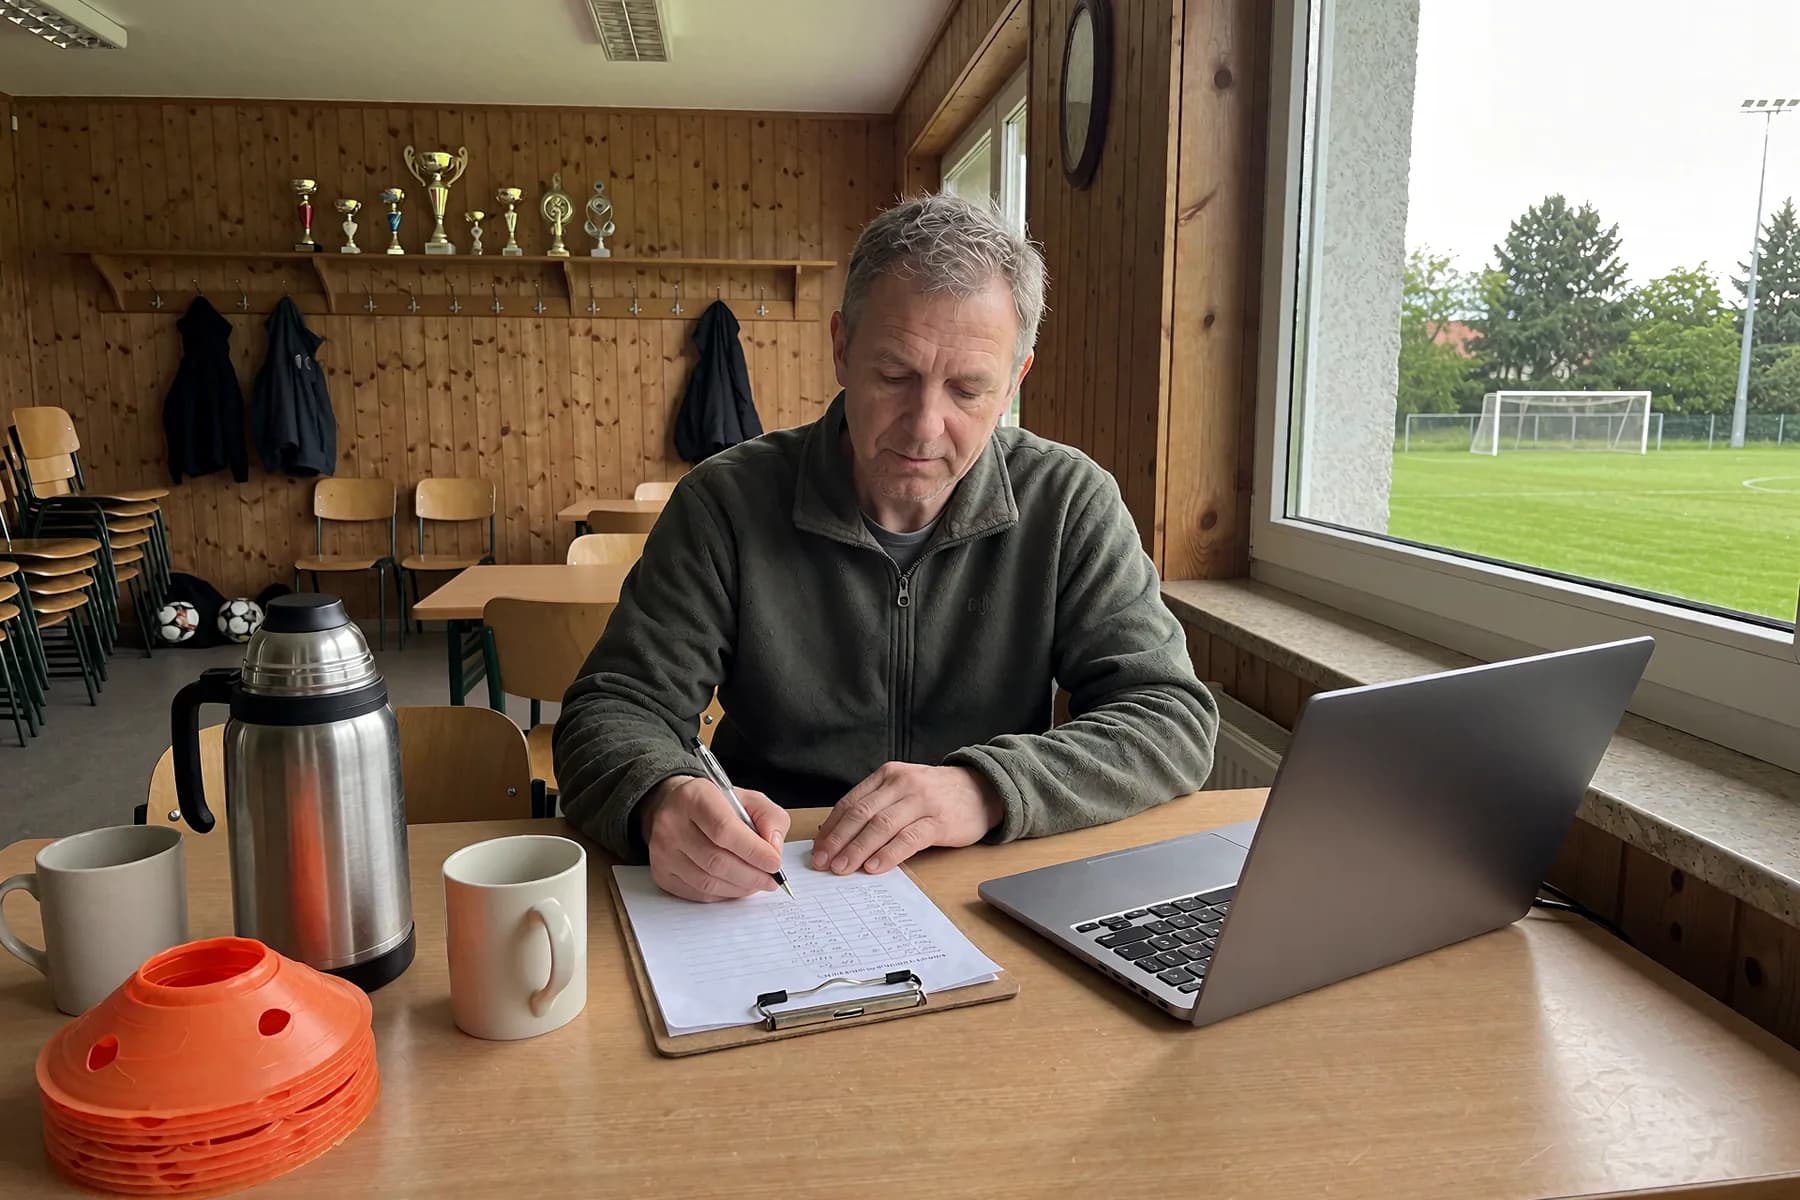
In shortClubs have to record their employees’ working time, for mini-jobbers additionally within seven days under section 17 MiLoG. Coaches and volunteers are not automatically employees, and their pay is tax-free up to 3,300 euros or 960 euros a year. MetronHR records employees’ working time with break calculation and supplies the hours per person to payroll.
- Made in GermanyDeveloped and hosted in Germany
- Certified data centreISO 27001, located in Germany
- Web, app and terminalBrowser, iPhone, Android, Mac, Windows
- GDPR compliantServers in Nuremberg and Falkenstein
Who in a club falls under which rule
The decisive question is not what an activity is called but how it is actually arranged. Working time law, social security and tax all hang on that.
- Instructor allowance
- 3,300 euros a year
- Volunteer allowance
- 960 euros a year
- Mini-job threshold
- 603 euros a month
- Recording duty
- for employees
The instructor allowance: 3,300 euros a year
Income from secondary activities as an instructor, trainer, educator or carer, or from comparable secondary activities, is tax-free up to 3,300 euros a year.
Governed by section 3 no. 26 EStG. Secondary means no more than a third of the working time of a comparable full-time occupation. The allowance applies per person and year, not per club. Anyone active at two clubs shares the same amount between them.
The volunteer allowance: 960 euros a year
For other secondary activities in the charitable sector, such as board work, groundskeeping or treasury duties, income is tax-free up to 960 euros a year.
Set out in section 3 no. 26a EStG. The two allowances cannot be combined for the same activity, but they can for different activities of the same person. Paying board members additionally requires the statutes to permit it, otherwise it jeopardises charitable status.
Volunteering is not an employment relationship, until it becomes one
Anyone working under instructions, integrated into fixed processes and paid an amount clearly exceeding their expenses is an employee, regardless of the label.
The standard is section 7 (1) SGB IV. The allowances in section 3 EStG say nothing about whether someone is an employee; they only govern the taxation of the income. An instructor with a fixed timetable working under instructions can be an employee even if their pay stays below 3,300 euros.
For employees the recording duty applies without exception
If the club employs staff, it must record the start, end and duration of daily working time. There is no exception for small or charitable employers.
The duty follows from section 3 (2) no. 1 ArbSchG as interpreted by the Federal Labour Court (decision of 13 September 2022, 1 ABR 22/21). For marginally employed staff section 17 (1) MiLoG is added, with a seven-day deadline and two years of retention. The limits of the Working Time Act apply too, and a weekend tournament changes nothing about that.
The key duties and how they are met day to day
| Duty | Source | With paper or Excel | With MetronHR |
|---|---|---|---|
| Record employees' working time | Section 3(2) no. 1 ArbSchG, Federal Labour Court 1 ABR 22/21 | time sheets with the treasurer | start, end and break, with break calculation |
| Mini-job: record within 7 days | Section 17(1) MiLoG | only when typed up at month end | when clocking in, on the same day |
| Record time beyond 8 hours, keep for 2 years | Section 16(2) ArbZG | binders in the office | stored as long as the account exists |
Record employees' working time
- Source
- Section 3(2) no. 1 ArbSchG, Federal Labour Court 1 ABR 22/21
- With paper or Excel
- time sheets with the treasurer
- With MetronHR
- start, end and break, with break calculation
Mini-job: record within 7 days
- Source
- Section 17(1) MiLoG
- With paper or Excel
- only when typed up at month end
- With MetronHR
- when clocking in, on the same day
Record time beyond 8 hours, keep for 2 years
- Source
- Section 16(2) ArbZG
- With paper or Excel
- binders in the office
- With MetronHR
- stored as long as the account exists
Further reading: Section 3 no. 26 EStG, section 3 no. 26a EStG · Section 7 (1) SGB IV, section 8 (1a) SGB IV · Section 3 (2) no. 1 ArbSchG, section 17 (1) MiLoG · Federal Labour Court, decision of 13 September 2022, 1 ABR 22/21
In detail, with examples: Time tracking in a club: who has to record and who does not
As at: November 2026. This is not legal advice; for a specific case in your business it is better to ask someone with a licence to practise.
Everything runs through one list, and that list knows no distinctions
Many clubs keep everyone involved in a single spreadsheet. That works until an inspection asks which of them were employees.
- Problem
Allowances get estimated
Whether someone has already used up the 3,300 euros or the 960 euros for the year is usually known only to the treasurer, who does the maths in December.
- Problem
Employees end up in the same list as volunteers
For one group the recording duty applies, for the other it does not. In a shared spreadsheet both are documented wrongly.
- Problem
Tournaments and holiday camps burst the limits
Ten hours a day are still ten hours at the summer fete. Without records nobody notices, and without compensation the breach stands.
Recording where it is mandatory
For employees and mini-jobbers, recording runs with automatic break calculation, and in the roster of the Professional plan with a rest period check. The tax-free allowances under section 3 nos. 26 and 26a EStG are still kept by payroll; MetronHR supplies the hours per person.
Working time on recordEmployees’ times are on record in March just as in December, without recalculating at the end of the year.
Features for clubs and charitable organisations
Built for mixed teams, volunteer structures and thin administration.
- File
Contract per person
Part-time, full-time or mini-job clearly on file
The contract decides what applies: target hours and an overtime account for employees, mini-job contracts without target hours.
- Overview
Monthly overview for payroll
Hours per person as Excel or a payroll file
At the end of the month, the hours per person are in the monthly Excel overview and in the payroll file for DATEV. The tax-free allowances are still calculated by payroll.
- Time
Recording for employees
Duty met, even in a small club
Start, end and break per working day, with automatic break calculation under section 4 ArbZG.
- Planning
Duties for events
Tournaments and festivals without paper chaos
In the Professional plan, assignments are posted, whoever wants to take one applies, and the line-up is visible at any time.
- Absence
Holiday and absences for employees
Requests digitally instead of by word of mouth
Holiday entitlement, approval and remaining days run in the same system as time tracking.
For the board and everyone involved
Volunteer-run administration needs tools that cost little time.
- Board and club office
Inspection-proof, without a post dedicated to it
- The administration runs on the side. Allowances, contributions and working hours still have to add up.
- Contracts, working times and absences are in one place, without anyone recalculating everything in December.
- Instructors and employed staff
Seeing your own times
- Are my recorded hours right, and how much leave do I have left?
- Your own times and remaining leave are in the app, without asking the club office.
Frequently asked questions from clubs
What clubs ask about allowances, status and the recording duty.
Question not answered here? Every step is explained in the help centre.
Send us a messageHow high are the instructor allowance and the volunteer allowance?
The instructor allowance under section 3 no. 26 EStG is 3,300 euros a year, the volunteer allowance under section 3 no. 26a EStG is 960 euros a year. Both apply per person and year, not per club.
Can we use both allowances for the same person?
Not for the same activity. For different, clearly separated activities of the same person the combination is possible, for example running training sessions and keeping the accounts.
Do we have to record working time for our volunteers?
No, as long as they are not employees. The recording duty in section 3 (2) no. 1 ArbSchG attaches to the employment relationship. What matters is the actual arrangement under section 7 (1) SGB IV, not the label in the contract.
When does volunteering become an employment relationship?
When the person works under instructions, is integrated into fixed processes and receives pay that clearly exceeds their actual expenses. The allowance under section 3 EStG changes nothing about that; it only governs taxation.
Does the Working Time Act apply at a weekend tournament too?
For employed staff yes, without exception. Eight hours per working day, ten with compensation within six calendar months or 24 weeks (section 3 ArbZG), plus breaks under section 4 and eleven hours of rest under section 5 ArbZG.
Other industries
Hospitality
Hospitality is named in section 2a SchwarzArbG. The seven-day deadline of section 17 MiLoG therefore applies to all employees, not just to mini-jobbers.
ViewCare
Care facilities are the only industry with two special routes on rest periods, and since the ECJ ruling standby duty counts in full as working time.
ViewHotels
Reception around the clock, housekeeping in the morning, breakfast from five. Three rhythms in one house, and accommodation falls under section 2a SchwarzArbG.
View
Employees, mini-jobs and assignments in one place
Working time recorded where it has to be, assignments planned and everything in one place. Try it free for 14 days.
- No credit card required
- Ready quickly
- Cancel monthly
- Full access to every feature
No credit card, cancel at any time